Alfamart: Well-capitalised to survive the market crisis
Beyond the volatility of capital markets, Alfamart remains a well-capitalised company with solid balance sheet. Minimarts ride the wave of modern trade retailing in a developing economy.
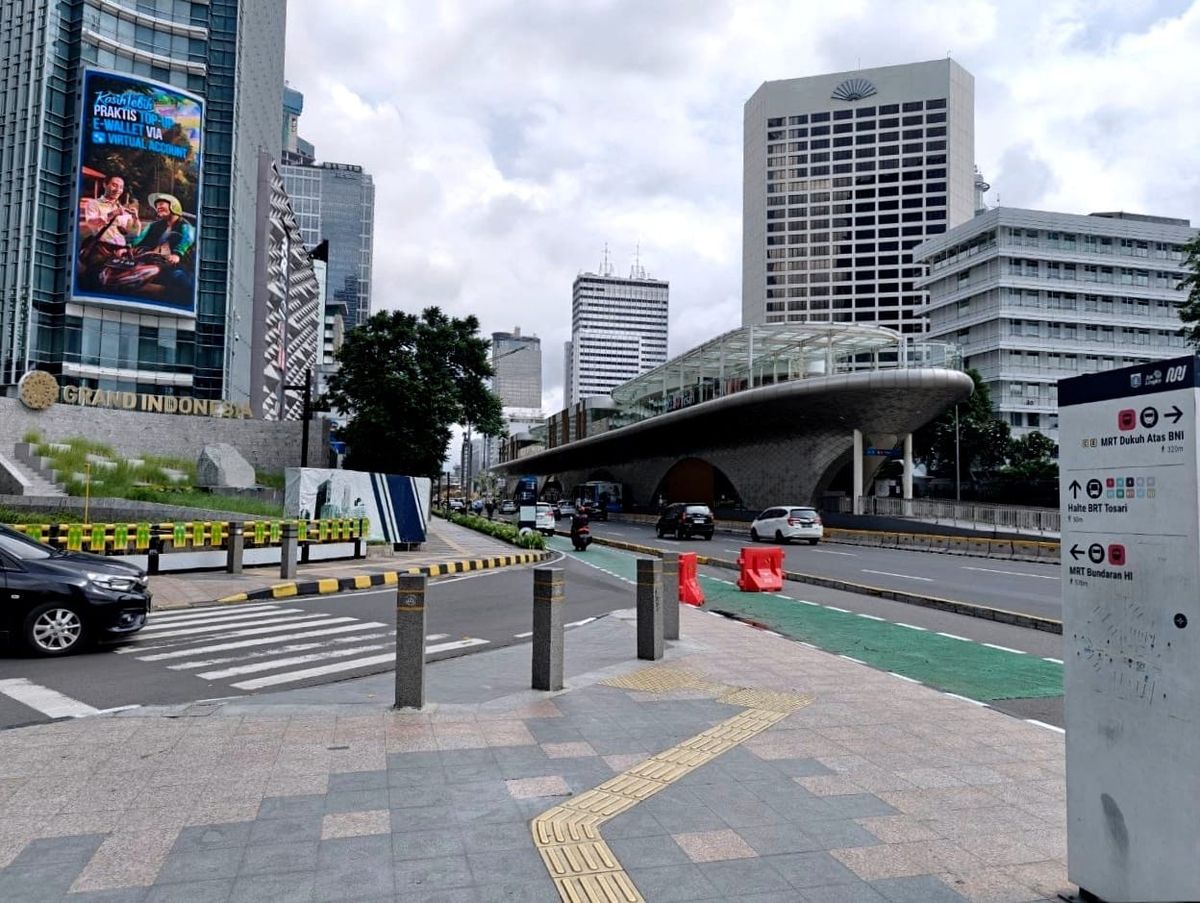
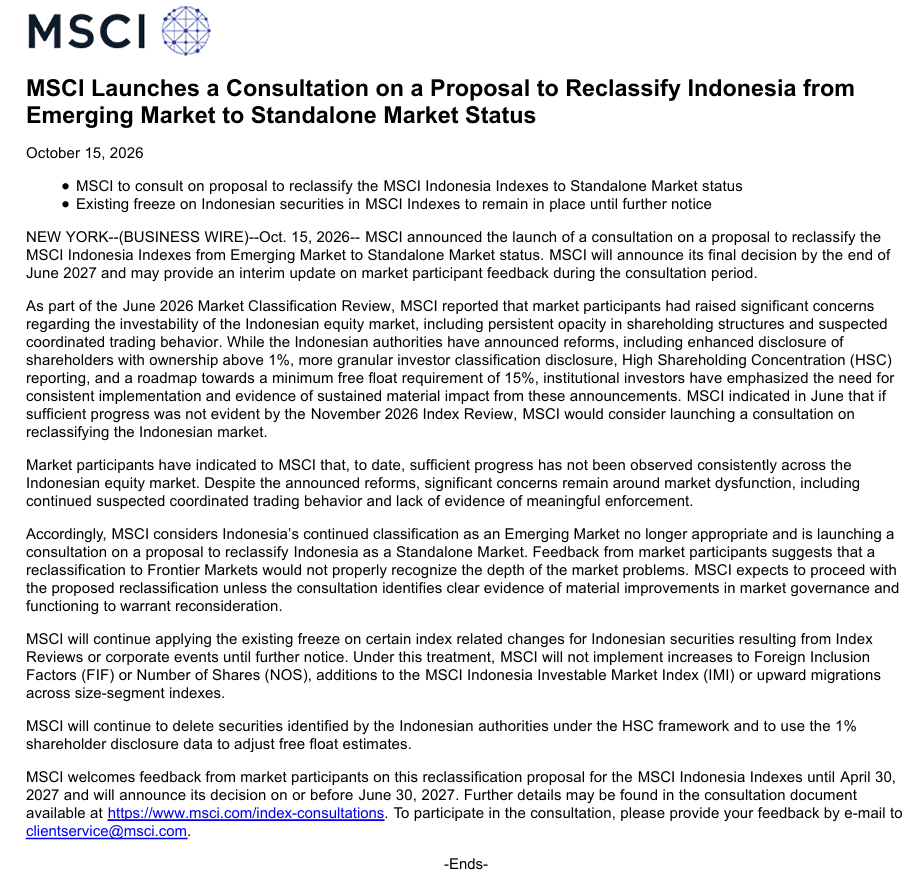
Indonesian equities have tumbled with the latest MSCI announcement of a potential downgrade. Months earlier, concerns have already surfaced on the possibility of Indonesia losing its emerging market status among rating agencies and index providers. While initial discussions at the start of the year pointed to an expectation of downgrading to frontier status, an update from MSCI this month opened up the consultation for a double downgrade to standalone market status.
Following this update, MSCI's decision will be postponed from November 2026 to next year by end of June 2027. That said, interim updates may be given, providing a window for Indonesia to pursue market reforms and address investor concerns. The severity of the announcement led to Indonesian equities facing a sell-off, with foreign investors re-evaluating the investability of the country.
While the macro factors of Indonesia are challenging and the equity market is alleged to be lacking in shareholder disclosures, the broad selling so far has given rise to long-term opportunities of investing in bellwethers of the Indonesian economy.
Indeed, overall instability and slow progress in market reforms do warrant a higher risk premium from investors. And international investors have to further bear the risk of foreign currency fluctuations. However, strong franchises like PT Sumber Alfaria Trijaya ('Alfamart') bore the blunt primarily due to their representation in the Indonesian equity market. With the stock down 70% from its peak, it is arguable whether the macro risks are more than priced in.
The vagaries of index flows are not new to the company. At a market capitalisation of a couple of billions US dollars, the company straddles between the definition of mid-caps and small-caps. At the same time, as a heavily-tracked component of the domestic equity market, a negative spiral can occur when rounds of selling and lower market capitalisation reinforces each other.
Beyond the technicalities of capital markets, Alfamart remains a well-capitalised company with solid balance sheet. The underlying business of operating minimarts rides the wave of modern trade retailing in a developing economy underpinned by a young populous demography. Competing head-on with Indomaret, the two minimart chains command the highest market shares in the country.
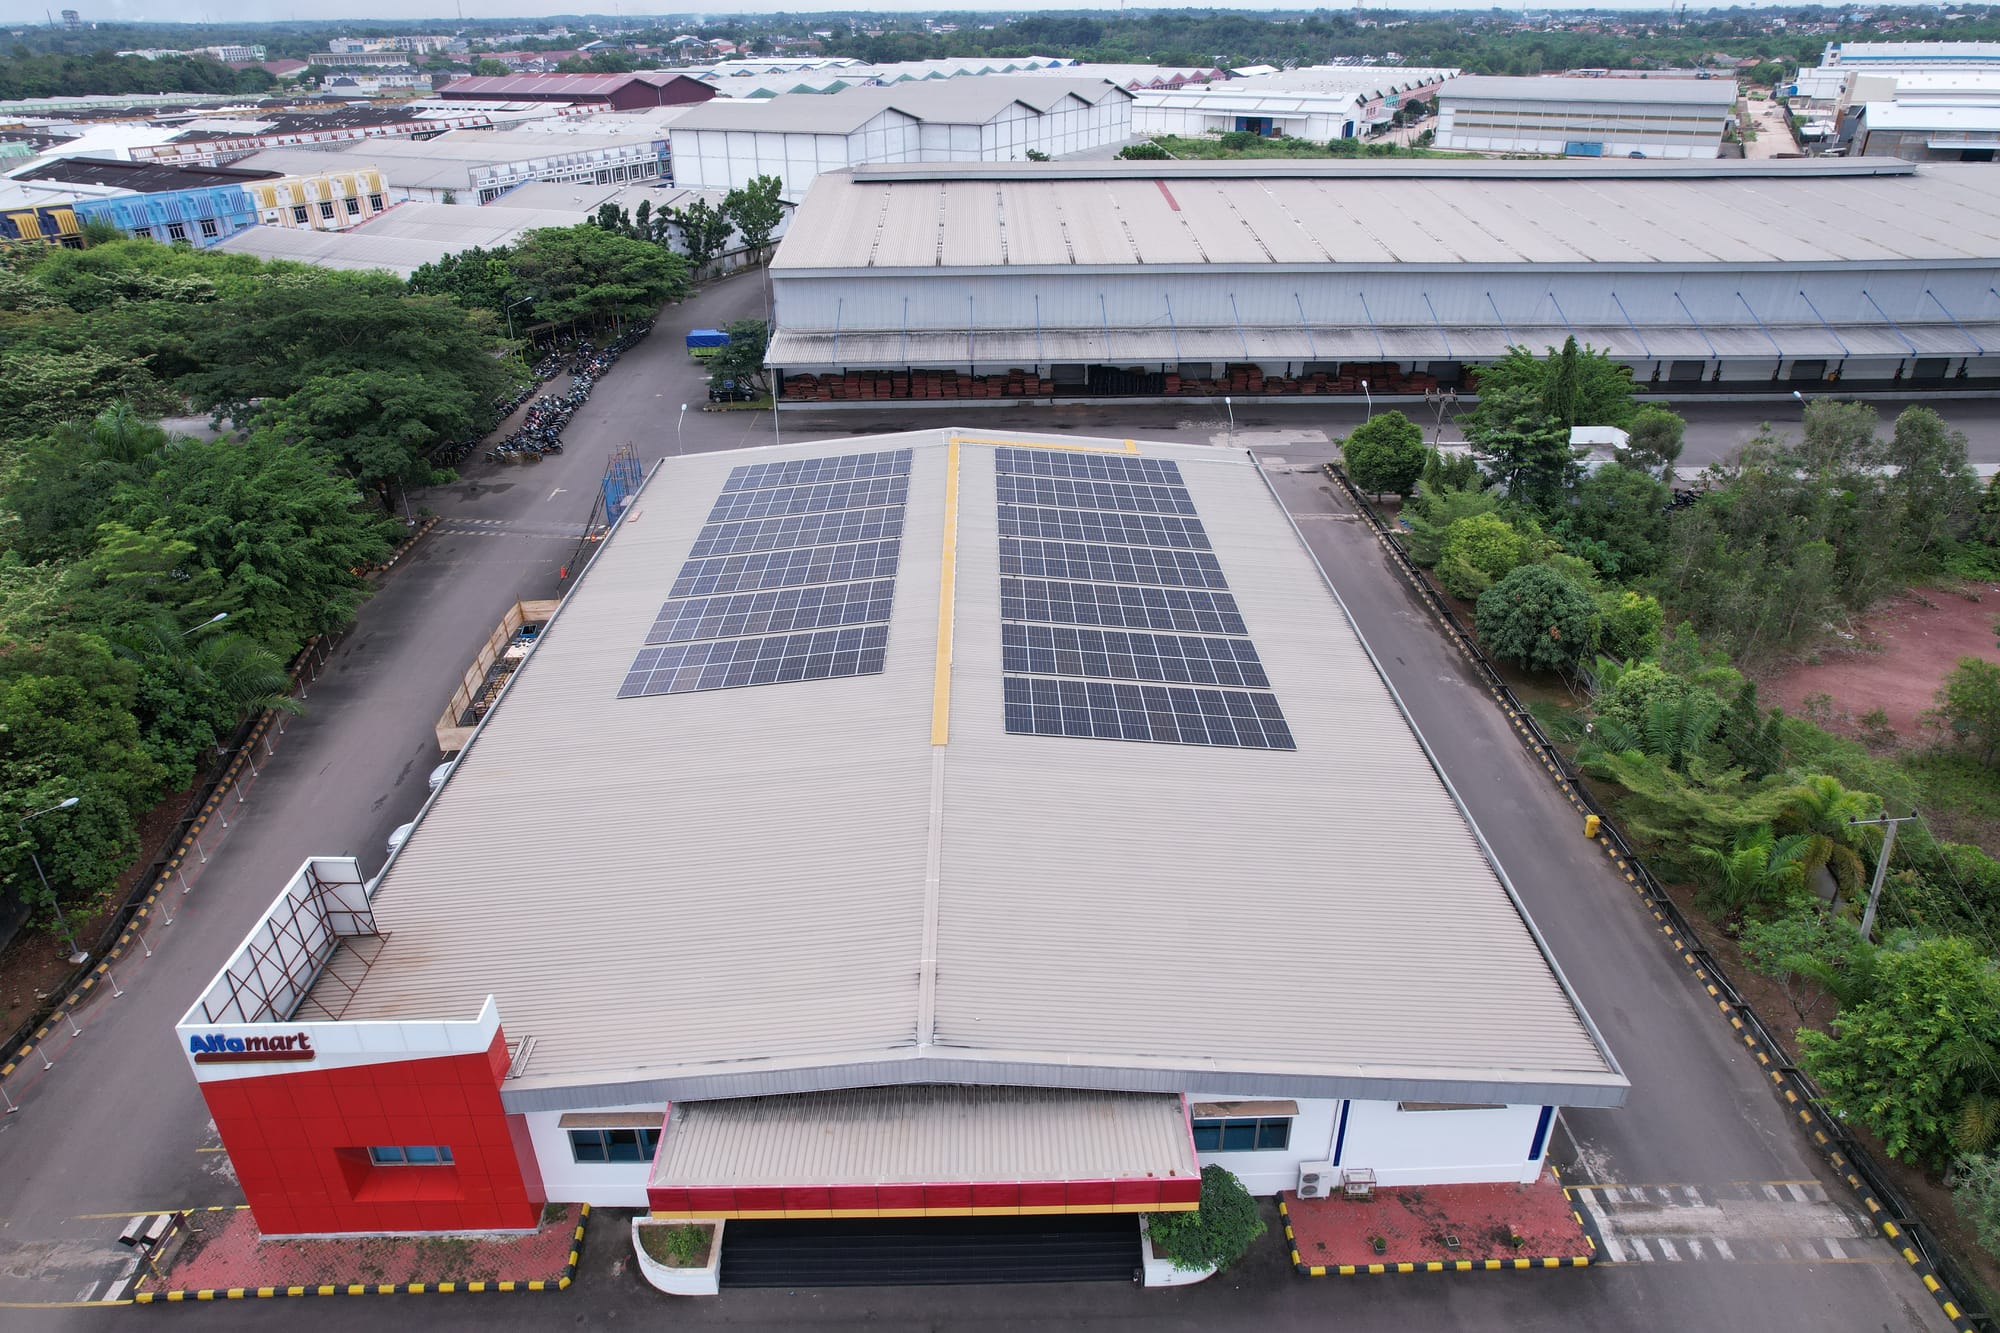
Key advantages of this business stem from how well distribution centres and supply chain support the sprawling network of stores. On this end, Alfamart’s density of largely company-owned stores serves many neighbourhood catchment areas and helps support large-scale complex of warehouses and depots.
Even before the market-wide turmoil took hold, surrounded by opaque ownership structure, stock market manipulation enabled by low float, and coordination of syndicates targeting IPOs, Alfamart was already facing real operation issues with regards to its own business growth.
For a minimart, consumer health is highly reflected in volume of sales. However, growth in recent quarters have been driven more so by price. Price-led growth may not be as sustainable without durable pricing power from branding, and branding is far less a moat in an industry like FMCG distribution. Therefore, relying on prices to increase average basket value is at best an interim measure to offset volume weakness before price increases ultimately lead to more customer groups switching away for good.
Confidence in defending operating margins is therefore key in this environment for Alfamart to set a fundamental floor to the stock valuation. As it stands, Alfamart has derated more than half to the current low teens forward price-to-earnings ratio.
Cost of living pressures are also proving to be a headwind not just for Alfamart, but the modern trade industry as a whole. Downtrading to traditional mom-and-pop retail will continue to reduce volume from modern trade while pricing out price-conscious segments of consumer demand. At the same time, policymakers may seek help from businesses to support wage growth in alleviating higher cost of living. With wages being a large cost component of Alfamart’s business, near-term investor concern of shrinking profit margins is fairly warranted.
All that said, what sets Alfamart apart in this crisis period of Indonesia's equity market cycle is the balance sheet cushion it has amassed going into these challenging times. Owing to the cash generative nature of the minimart business, a net cash position coupled with minimal necessary capex outlays placed the company in good stead compared to more cyclical Indonesia companies such as commodity-linked businesses.
Even if the macroeconomic conditions are not nearing a bottom, Alfamart is likely one of the larger domestic company with the ability to manage and tide through this crisis.